Tensions in the Middle East are rising. The geopolitical situation around Iran and the strategic Strait of Hormuz is creating uncertainty in global markets. Energy prices in particular are reacting quickly. But what does this mean for the steel market? And what should European and Belgian steel traders expect?
No direct shock in steel prices yet
For now, there has been no immediate or sharp increase in steel prices directly linked to the tensions in the Middle East. Unlike oil and gas markets, Iran does not play a dominant role in steel exports to Europe.
However, this does not mean the steel market is immune to geopolitical developments. The impact is mainly indirect, through factors that are essential to steel production and global trade.
Rising aluminium prices highlight sensitivity of raw material markets
The impact of geopolitical tensions is already visible in other metal markets. Aluminium prices are currently rising, partly due to uncertainty about energy supply, logistics routes and broader tensions in raw material markets.
Aluminium production, like steel production, is highly energy-intensive. When oil and gas prices rise or transport flows are disrupted, aluminium prices often react more quickly. Recent price movements illustrate how geopolitical risks can rapidly translate into higher costs for industrial metals.
For the steel market, this is an important indicator. While steel prices have not yet reacted directly to the situation in the Middle East, prolonged increases in energy and logistics costs could eventually put upward pressure on global steel prices.
Energy prices remain the main transmission channel
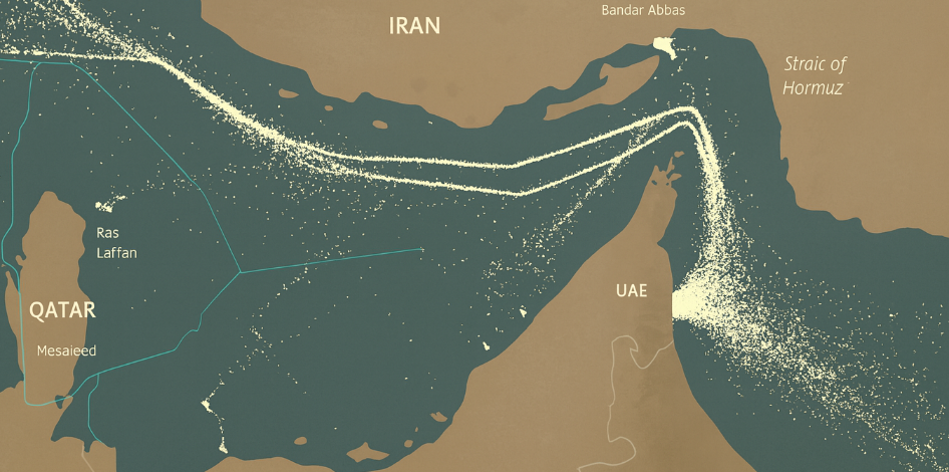
The Strait of Hormuz is a critical transit route for a significant share of global oil and LNG shipments. When tensions rise in the region, energy markets tend to react almost immediately.
For the steel industry, this is significant because steel production is extremely energy-intensive. Higher oil, gas and electricity prices increase production costs, especially for plants using electric arc furnaces.
If energy prices remain elevated for a longer period, this could push global steel prices upward.
Logistics uncertainty
In addition to energy costs, logistics also play a role. Maritime routes around the Persian Gulf are strategically important for global raw material trade.
If shipping companies begin avoiding certain routes or choose longer alternatives, this often results in:
- higher insurance premiums for vessels
- rising freight rates
- longer delivery times for raw materials and semi-finished steel products
Even though Europe is not directly dependent on steel imports from Iran, disruptions in global trade flows and rising freight costs can still affect European steel prices.
What does this mean for Belgian steel traders?
In the short term, Belgian steel traders should keep an eye on several factors:
1. Energy price volatility
Energy remains a key cost component in steel production.
2. Rising logistics costs
Transport costs for international shipments may increase when trade routes are under pressure.
3. Greater market volatility
Geopolitical uncertainty often leads to shorter price cycles and faster market shifts.
Two possible scenarios
Scenario A: temporary tensions
If tensions stabilise, the impact on steel prices will likely remain limited to temporary fluctuations through energy and freight costs.
Scenario B: prolonged escalation
If trade through the Strait of Hormuz is disrupted for a longer period, energy prices could remain structurally higher. In that case, global steel prices may come under stronger upward pressure.
Looking ahead
Although steel prices have not yet reacted sharply, geopolitical tensions once again demonstrate how closely energy, logistics and raw material markets are connected.
For steel traders, closely monitoring geopolitical developments and energy markets remains essential.